Unpaid employment taxes? 5 tips of what to expect from the IRS
 Unpaid employment taxes are a big “No No” in the eyes of the IRS. Owing these types of taxes results in heavy IRS collection activity and generally assignment to a local revenue officer. Revenue officers have a great deal of power and are able to garnish wages, levy bank accounts and break apart your business.
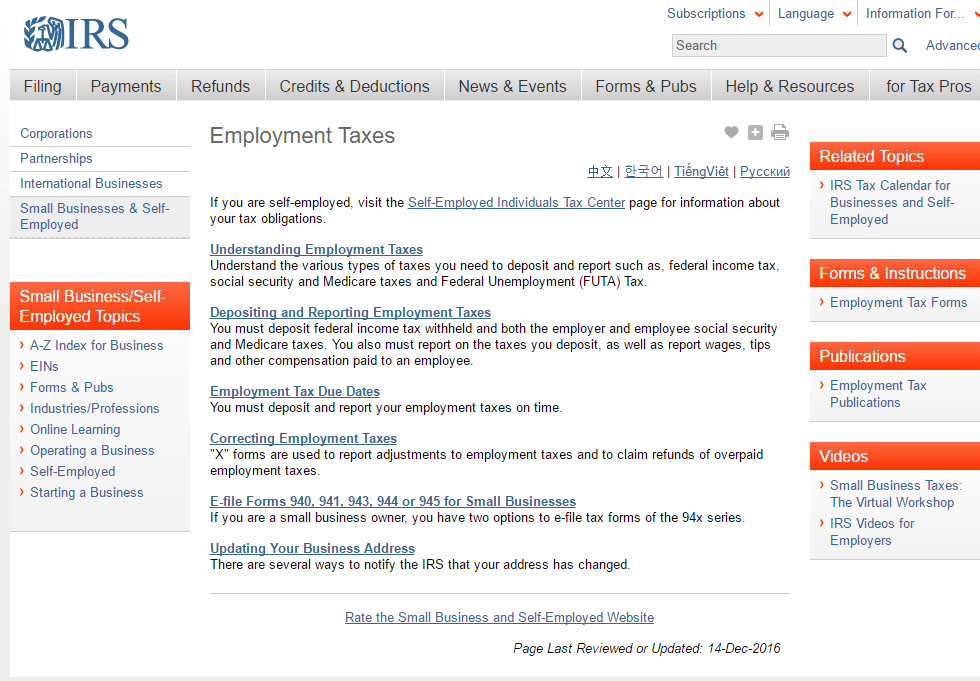
Employment taxes are made up of the following:
- The federal income tax withheld from employee pay and paid to the IRS
- Social Security and Medicare taxes (called “FICA taxes”) withheld from employee pay and paid to the IRS (these are also called “payroll taxes” reported on IRS form 941).
- The Additional Medicare tax imposed on higher-earning employees.
- Federal unemployment taxes (FUTA tax) paid by employers based on number of employees and unemployment rates.
- Self-employment taxes, which are the Social Security and Medicare taxes paid by self-employed business owners.
If your business has unpaid employment taxes, here’s what you can expect:
1. An unannounced visit to your business.
The revenue officer will unexpectedly drop by and try to snoop around. Do not be afraid. You do not have to comply with any requests to view your business or records unless (1) you agree or (2) if he or she provides you with a court order (which is rare on the first visit).
First impressions count so be respectful and courteous. The revenue officer will ask many questions and your answers will be remembered and written down. So, be careful of what you say…and be respectful.
If you are in the process of retaining a tax attorney to represent you with your unpaid employment taxes, kindly tell the revenue officer this and refer him or her to your new attorney. They will respect you for that. And no, it does not look like you are trying to hide anything if you hire an attorney. It will only help you.
2. Issuance of a Final Notice of Intent to Levy.
The IRS nor the revenue officer can take collection action until 30 days after a Final Notice of Intent to Levy is issued. You may have received this certified from the IRS already or may directly receive this from the revenue officer. Collection action includes garnishing wages and levying bank accounts and customer receivables.
Before the thirty days is up, you have an appeal right to file a request for an administrative meeting with an IRS appeals officer. This is known as a Collections Due Process Hearing or CDP.
The purpose of a CDP appeal is to discuss alternatives to the intent to levy and reach case resolution without enforcement.
3. Getting your business into compliance and financial discovery.
If your business has not filed certain tax returns, the revenue officer will insist upon all such returns being filed. Resolution will not be a possibility without tax return compliance. Also, he or she will want IRS form 433B to be filled out which is a financial statement for the business. A Summary of Taxpayer Contact (Form 9297) will be left with you which is a summary of what the revenue officer wants and when things are due.
And, do not miss a revenue officer deadline for documents and information due. Always keep them posted as to your status and if you need more time, be sure to call them and let them know of any delays. They are usually good about extending the time if you communicate with them and are really working hard on providing any all information necessary.
4. Discuss and make plans to get your business “current” with employment taxes.
The revenue officer will make demands for your business to start paying employment taxes if you are not current. Then they will turn to looking for ways to pay any past employment taxes owed.
They will investigate pretty much all business operations and immediately find ways for your business to get into compliance and make those deposits. Be ready for change.
5. Investigation of the Trust Fund Recovery Penalty.
This is possibly the worst result for a business owner, officers or others responsible for failure to withhold employment taxes. Being assessed with a Trust Fund Recovery Penalty means you essentially become “personally” liable for the unpaid employment taxes of the business. Yes, this means the IRS can collect upon you personally through wage garnishments, bank levies and filing tax liens on your property.
According to the IRS website, “A responsible person is a person or group of people who has the duty to perform and the power to direct the collecting, accounting, and paying of trust fund taxes. This person may be:
- An officer or an employee of a corporation,
- A member or employee of a partnership,
- A corporate director or shareholder,
- A member of a board of trustees of a nonprofit organization,
- Another person with authority and control over funds to direct their disbursement,
- Another corporation or third party payer,
- Payroll Service Providers (PSP) or responsible parties within a PSP
- Professional Employer Organizations (PEO) or responsible parties within a PEO, or
- Responsible parties within the common law employer (client of PSP/PEO).
The Revenue Officer will want to know why employment taxes were not paid. That question will be answered by starting an investigation to find who was responsible in the business for dropping the ball. If the revenue officer interviews someone and finds they were involved in the decision making of not withholding employment taxes to the IRS, they may be charged with a Trust Fund Recovery Penalty.
It is best to contact a tax attorney who specializes in payroll tax debt relief and the Trust Fund Recovery Penalty. A skilled attorney will review your financial situation and strategize with regard to resolving your employment taxes.
The San Diego Tax Attorneys at Delia Law have many years of tax resolution experience and will competently represent you before the IRS. Please call for a no-cost tax attorney consultation at (619) 639-3336 especially if you have unpaid employment taxes. We look forward to helping you.
This blog post is not intended as legal advice and should be considered general information only.