Can’t pay your IRS tax debt? Currently Not Collectible Status May Be an Option
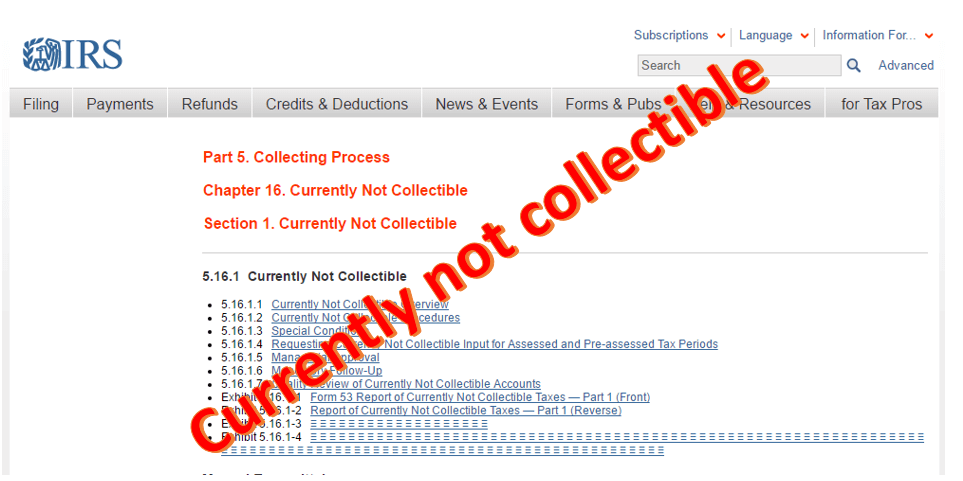 Are you falling behind on filing tax returns, paying taxes, or both? The IRS may give you a break if you are found to be experiencing extreme financial hardship. They may place certain delinquent tax cases in a “currently-not-collectible” (“CNC”) status, if they determine that there is no ability to pay.
A CNC status is worth looking into as the alternative can be quite frightening. If you cannot pay and do nothing, the IRS will begin enforced collection action, which may include garnishing your wages, levying your bank accounts, filing IRS tax liens against your property, and seizing other assets.
What are the pros and cons to IRS Currently Not Collectible Status?
If you are able to prove that you are unable to pay IRS back taxes due to “economic hardship,” then the IRS will close your case by putting it in a “CNC” status. There are some pros and cons to this you should be aware.
Pros to an IRS Currently Not Collectible status
- it protects you from the aggressive tactics of the IRS collection division.
- you will not be subject to bank levies or wage garnishments while in this status.
- it is a great way to run out the Collection Statute Expiration Date (“CSED”) if you qualify. The IRS has ten years to collect on an IRS tax debt, and this ten-year period continues to run even though you are in a CNC status. Many taxpayers in CNC status can remain there until all of their tax liabilities expire.
Cons to an IRS Currently Not Collectible Status
- it is not a permanent solution. The tax is not forgiven or compromised, and interest and penalties continue to accrue.
- the IRS commonly places an IRS tax lien on your property if this status is granted. This can ruin your credit.
- the IRS will continue to review your financial situation to see if has improved. They generally review once a year by checking reports from third parties (e.g. employers, banks, etc.).
- the IRS may ask for all unfiled tax returns to be filed before they will place your account in CNC status. This may create a hardship as tax returns are expensive to prepare.
- the IRS gains banking and wage information when applying for this status making it easier for them to collect upon you if you are not approved for this status. So, be sure you are a good candidate for this status going in.
Steps to qualify for a Currently Not Collectible status
- Determine whether your IRS allowable monthly expenses are greater than your “gross” monthly income and that your assets are much less than your total IRS back tax liability. If this is true, you will likely qualify for currently not collectible status. It is important to note that allowable monthly expenses must be related to life, health, welfare, or the production of income. The IRS provides some basic guidelines as to what and how much is allowable called the IRS Collection Financial Standards.
- If you have unfiled tax returns, prepare and file those immediately if you can.
- Complete IRS Form 433-F. This form is also called a Collection Information Statement which will, when filled out, will show your gross monthly income, monthly expenses and assets. It is used by the IRS to obtain current financial information necessary for determining how a wage earner or self-employed individual can satisfy an outstanding tax liability.
- Call the IRS collections department at (800) 829-3903 and state that you are experiencing financial hardship and would like your account to be placed in a Currently Not Collectible status. They will take all information on your 433F. They may also request additional information and documentation to substantiate the information on the 433F.
It is best to contact a tax attorney who specializes in resolving IRS tax debt. A skilled attorney will review your financial situation and strategize as to whether pursuing a CNC status is a viable option. The San Diego Tax Attorneys at Delia Law have many years of tax resolution experience and will competently represent you before the IRS. Please call for a no-cost tax attorney consultation at (619) 639-3336. We look forward to helping you.
This blog post is not intended as legal advice and should be considered general information only.